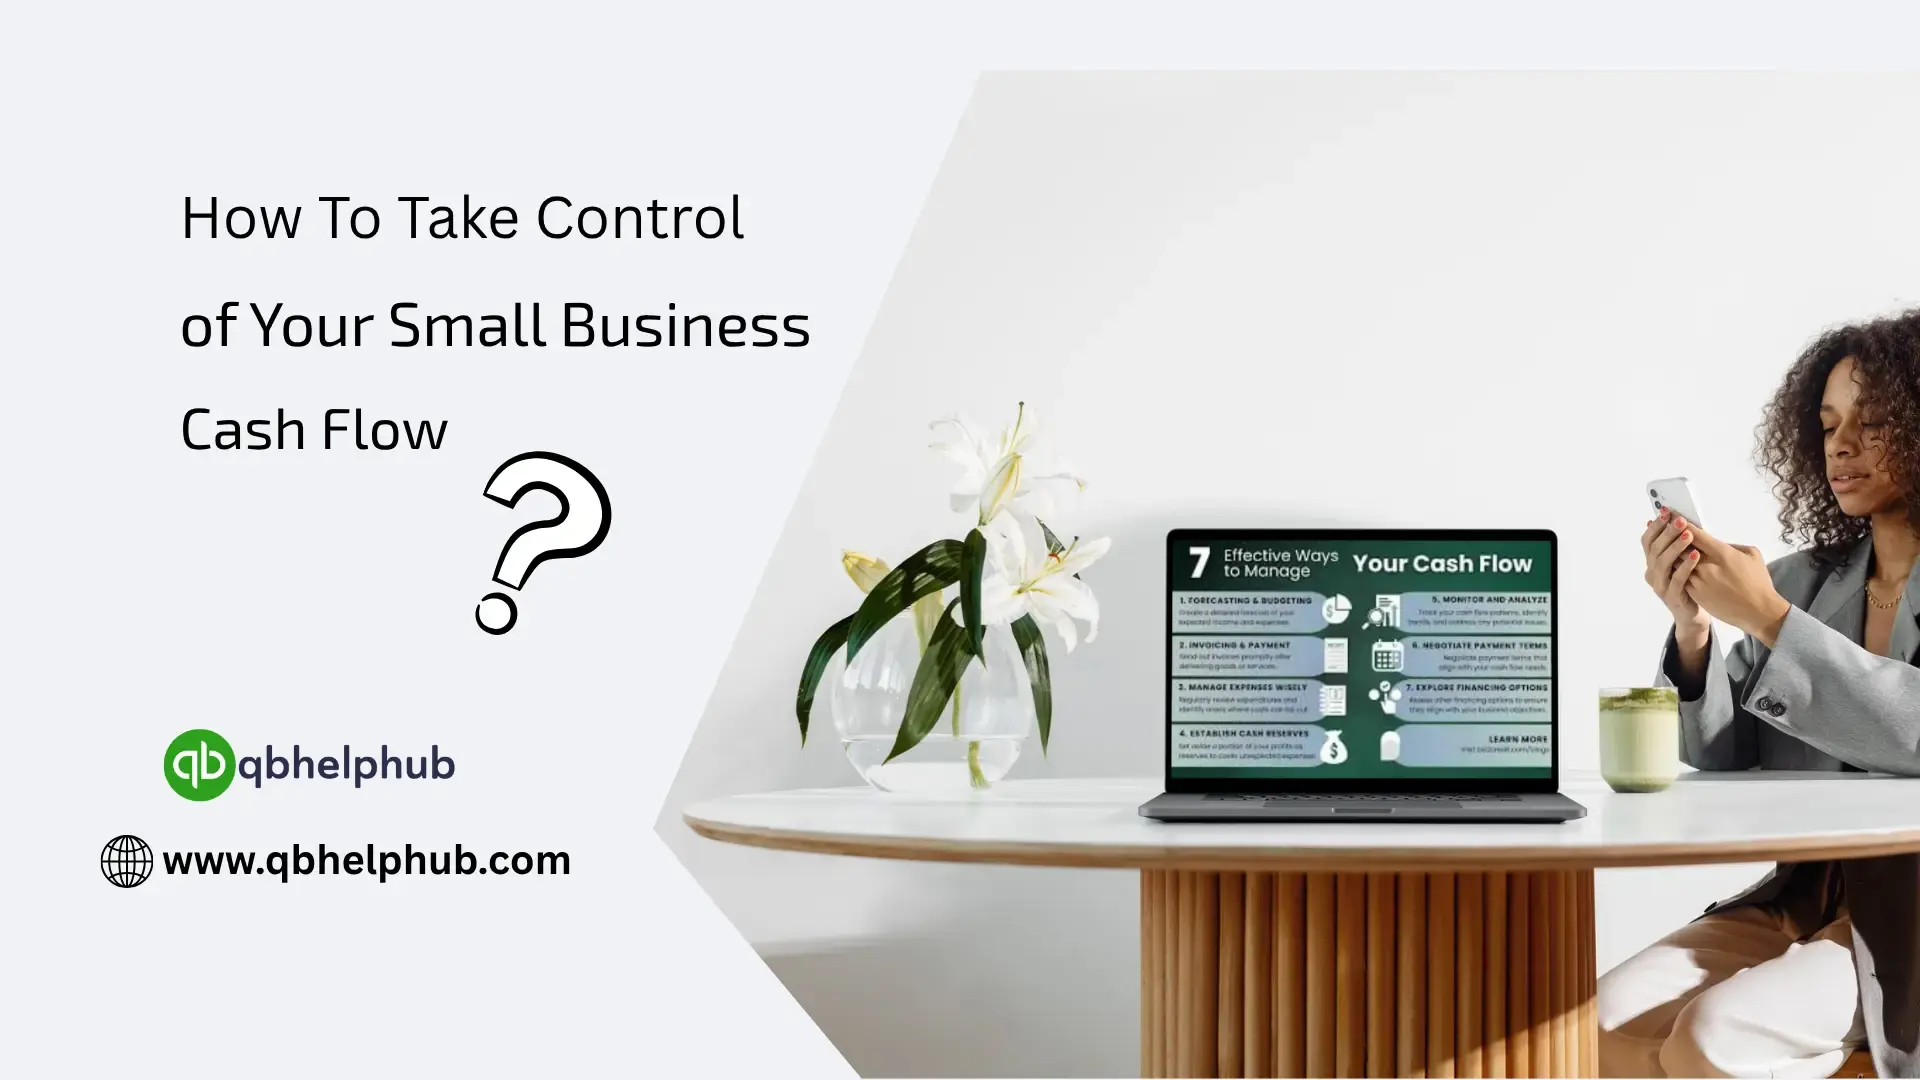
Cash flow can make or break a small business. It’s not just about how much money you’re bringing in it’s about how well you manage what’s coming and going on a daily, weekly, and monthly basis. When cash flow is tight, even profitable businesses can hit a wall. The good news? You don’t need to be a financial expert to keep your cash flow under control. With a few clear steps and ongoing habits, you can manage your cash more confidently and avoid the panic that comes with an empty bank account at the wrong time.
1. Understand What Cash Flow Really Means
Let’s start with the basics. Cash flow is simply the movement of money in and out of your business. The cash coming in could be from customer payments, loan proceeds, or investments. The cash going out? That’s your expenses like rent, payroll, supplier payments, and everything else you spend to keep the doors open.
What really matters is timing. You might be making great sales, but if your customers pay you 60 days later and your bills are due now, your business can still struggle. That’s why managing cash flow is more than just tracking profit it’s about managing timing and liquidity.
Read Also: How to Use QuickBooks for Small Business Accounting?
2. Track Every Dollar Coming in and Going Out
If you’re not already tracking cash flow regularly, now is the time to start. It doesn’t have to be fancy. You can use accounting software like QuickBooks or even a simple spreadsheet to start.
Record all sources of income and categorize your expenses. Look at the trends weekly and monthly. Are your revenues fairly steady, or do they spike and dip? Do some expenses seem to creep up more than expected? Having this visibility helps you prepare for lean months and understand where your money tends to disappear.
3. Create A Realistic Cash Flow Forecast
This is one of the most powerful tools for small business owners. A cash flow forecast lets you look ahead usually for the next 6 to 12 months to predict how much money will be coming in and going out.
Start with your known income (like recurring client payments or regular sales) and subtract expected expenses (like rent, payroll, and inventory). Then add in variables seasonal slowdowns, new hires, or big one-time purchases. Seeing everything laid out helps you spot upcoming cash shortfalls and plan around them before they happen.
4. Speed Up Incoming Payments Whenever Possible
If your customers or clients are slow to pay, your cash flow suffers even if your sales numbers look great on paper. To improve incoming cash, try shortening your payment terms or offering early payment discounts. For example, you could offer 2% off the invoice total if they pay within 10 days instead of 30.
Also, don’t be shy about sending reminders. Automated invoice follow-ups help a lot. The longer an invoice sits unpaid, the lower your chances of collecting it without effort.
5. Delay Outgoing Payments Strategically
Just as you want to get paid faster, you should also be smart about when you pay others. Unless there’s a discount for early payment, wait until the due date to pay vendors. This keeps cash in your account longer, which can make a big difference.
That said, don’t go overboard. You don’t want to damage supplier relationships or rack up late fees. The goal is to balance outgoing payments to match your cash inflow without risking your reputation.
6. Monitor Inventory and Reduce What’s Unnecessary
If you sell products, keeping too much inventory ties up cash you could be using elsewhere. Look at your past sales and figure out what sells steadily versus what just sits on the shelf.
Try using just-in-time ordering if it works for your business. That way, you only stock what you actually need, and your money stays liquid instead of sitting in storage.
7. Plan For Seasonal Ups and Downs
Most businesses don’t have a consistent cash flow all year. Retailers often earn more in Q4, while contractors may see a slowdown in the winter. These cycles aren’t bad, but they can cause trouble if you’re not prepared.
Use your past years’ data to understand your slow periods. Build up cash reserves during busy times so you can glide through the slow ones without relying on expensive short-term loans or credit cards.
8. Keep A Cash Reserve for Emergencies
Every business no matter how stable should have some emergency cash on hand. Whether it’s to cover an unexpected equipment breakdown or a sudden dip in sales, a buffer buys you time and reduces stress.
Even setting aside a small percentage of monthly profits can add up. Aim for at least one to two months’ worth of operating expenses in your reserve over time.
9. Evaluate Expenses with a Sharp Eye
Review your business expenses regularly. You might be surprised how much you’re paying for tools, software, or subscriptions you no longer use or need.
Also, look for opportunities to renegotiate contracts or seek more affordable options for services like insurance, shipping, or even utilities. Keeping your fixed costs low gives your business more breathing room when income slows down.
10. Use Tools That Simplify Cash Flow Management
There’s no need to do everything manually. Tools like QuickBooks Online, Xero, or even your business bank’s dashboard can give you cash flow snapshots, help with forecasting, and even automate parts of your invoicing or reminders.
The easier it is to keep track of your cash, the more likely you are to stay on top of it. Technology doesn’t replace decision-making, but it helps you make smarter decisions with less effort.
Read Also: What Types of Businesses Can Use QuickBooks Online?
Final Thoughts
Controlling your cash flow isn’t about having more money it’s about being smart with the money you already have. The better you get at tracking, forecasting, and adjusting your financial strategy, the fewer surprises you’ll face. Even a few small changes can make a big impact on your business’s long-term stability. So, take the time to look closely at your numbers, build better habits, and keep your business running with confidence even when things get unpredictable.
Get In Touch with Us
If you are interested to know more about QuickBooks and basic troubleshooting steps, we are here to help you through our dedicated customer service team. Fill out the customer response form or feel free to reach to us at support@qbsolved.com Our highly competent team is here to solve all your queries regarding QuickBooks.